Free procurement template
FTA Decision 13 Supplier and Supply Verification Checklist
One-page A4 checklist for the supplier and supply checks in FTA Decision No. 13 of 2026, completed before you deduct input tax.
Last updated: 19 October 2026. Checked against the Decision text on tax.gov.ae: 15 October 2026.
How to use: adapt this template to your organisation's jurisdictions, sector, risk appetite and delegation of authority. Assign accountable owners and obtain legal or specialist review where required.
For what each article requires and why, read the full guide: FTA Decision No. 13 of 2026: supplier verification before input-tax deduction.
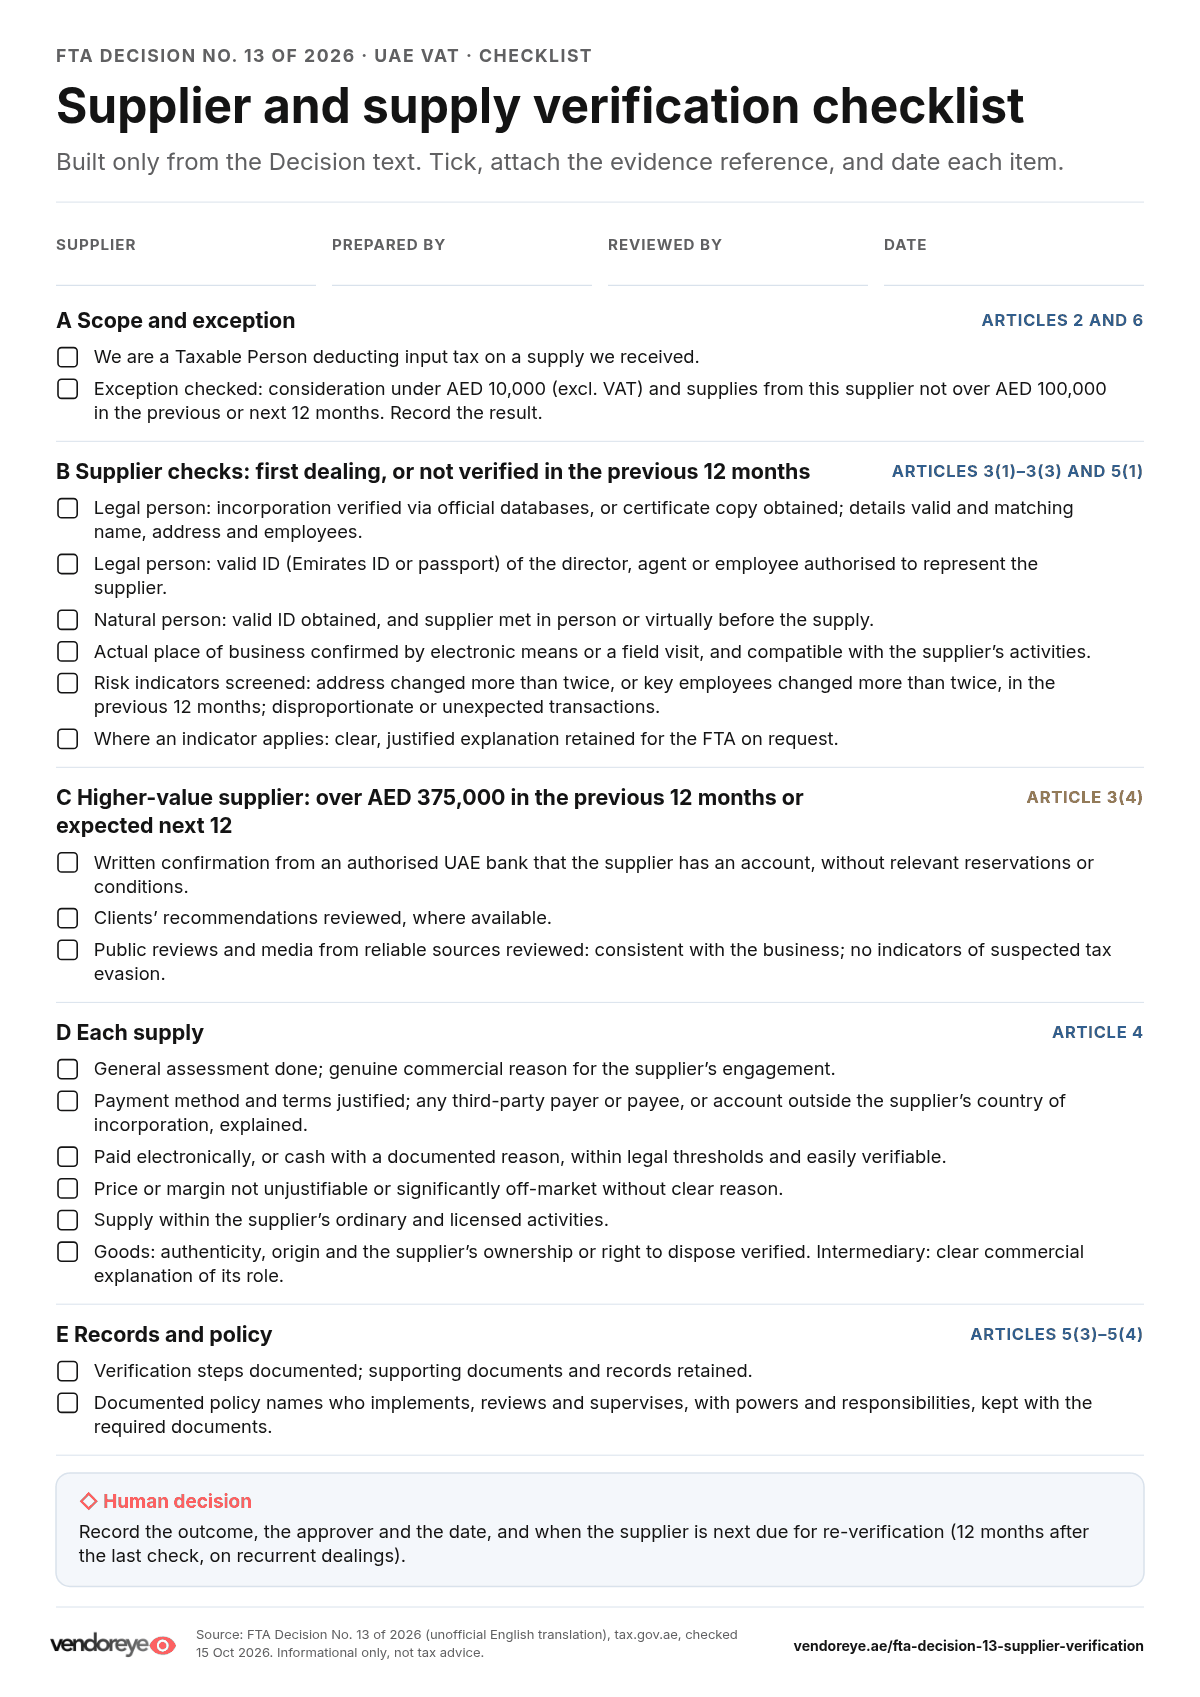
| Section | Check | Article | Evidence | Owner |
|---|---|---|---|---|
| A Scope | We are a Taxable Person deducting input tax on a supply we received | Arts. 1-2 | Note on the supply and the input-tax claim | Tax |
| A Scope | Exception: consideration under AED 10,000 (excl. VAT), and supplies from this supplier not over AED 100,000 in the previous or next 12 months. Record the result. | Art. 6 | Exception note with the 12-month total | AP / Tax |
| B Supplier | Legal person: incorporation verified through official databases, or certificate of incorporation obtained; details valid and matching name, address and employees | Art. 3(1) | Official-database extract or certificate copy | Procurement |
| B Supplier | Legal person: valid ID (Emirates ID or passport) of the director, agent or employee authorised to represent the supplier | Art. 3(1) | ID copy, stored once on the supplier record | Procurement |
| B Supplier | Natural person: valid ID obtained, and the supplier met in person or virtually before the supply | Art. 3(1) | ID copy; meeting note | Procurement |
| B Supplier | Actual place of business confirmed by appropriate electronic means or a field visit, and compatible with the supplier's activities | Art. 3(2) | Verification result or visit record | Procurement |
| B Supplier | Risk indicators screened: address changed more than twice, or key employees changed more than twice, in the previous 12 months; disproportionate or unexpected transactions | Art. 3(3) | 12-month change history; transaction review | Compliance |
| B Supplier | Where an indicator applies: clear, justified explanation retained and available to the FTA on request | Art. 3(3) | Signed explanation | Compliance |
| C Over AED 375,000 | Written confirmation from an authorised UAE bank that the supplier has a bank account, without relevant reservations or conditions | Art. 3(4)(a) | Bank confirmation letter | Treasury |
| C Over AED 375,000 | Clients' recommendations reviewed, where available | Art. 3(4) | Dated note with sources | Compliance |
| C Over AED 375,000 | Public reviews and media from reliable sources reviewed: consistent with the business; no indicators of suspected tax evasion | Art. 3(4)(b) | Dated review note with sources | Compliance |
| D Each supply | General assessment done; genuine commercial reason for the supplier's engagement | Art. 4 | PO or contract rationale | Requester |
| D Each supply | Payment method and terms justified; any third-party payer or payee, or account outside the supplier's country of incorporation, explained | Art. 4 | Payment record and explanation | AP |
| D Each supply | Paid electronically, or cash with a documented reason, within the applicable thresholds and easy to verify | Art. 4 | Payment record | AP |
| D Each supply | Price or margin not commercially unjustifiable or significantly off-market without a clear reason | Art. 4 | Price comparison | Procurement |
| D Each supply | Supply within the supplier's ordinary and licensed activities | Art. 4 | Trade licence activity check | Procurement |
| D Each supply | Goods: authenticity, origin and the supplier's ownership or right to dispose verified. Intermediary: clear commercial explanation of its role. | Art. 4 | Origin and ownership evidence | Procurement |
| E Records | Verification steps documented; supporting documents and records retained | Art. 5(3) | Verification log | Finance |
| E Records | Documented policy names who implements, reviews and supervises, with powers and responsibilities, kept with the required documents | Art. 5(4) | Approved policy | Finance leadership |
| Sign-off | ◇ Human decision: record the outcome, the approver, the date, and when the supplier is next due for re-verification (12 months after the last check, on recurrent dealings) | Art. 5(1) | Signed checklist | Approver |
Run section B on first dealing, and again on recurrent dealings once the supplier has not been verified for 12 months. Run section D on every supply. Owners are a suggestion; the Decision does not assign roles beyond requiring a documented policy.
Related: FTA Decision 13 guide · How to complete the checklist · Vendor due-diligence checklist · Vendor onboarding policy guide · All templates